Written by Bryan Lutz, Editor at Dollarcollapse.com:
The Federal Reserve has two main jobs: keep inflation under control and support a strong labour market.
Oil above $100 a barrel makes both of those jobs harder.
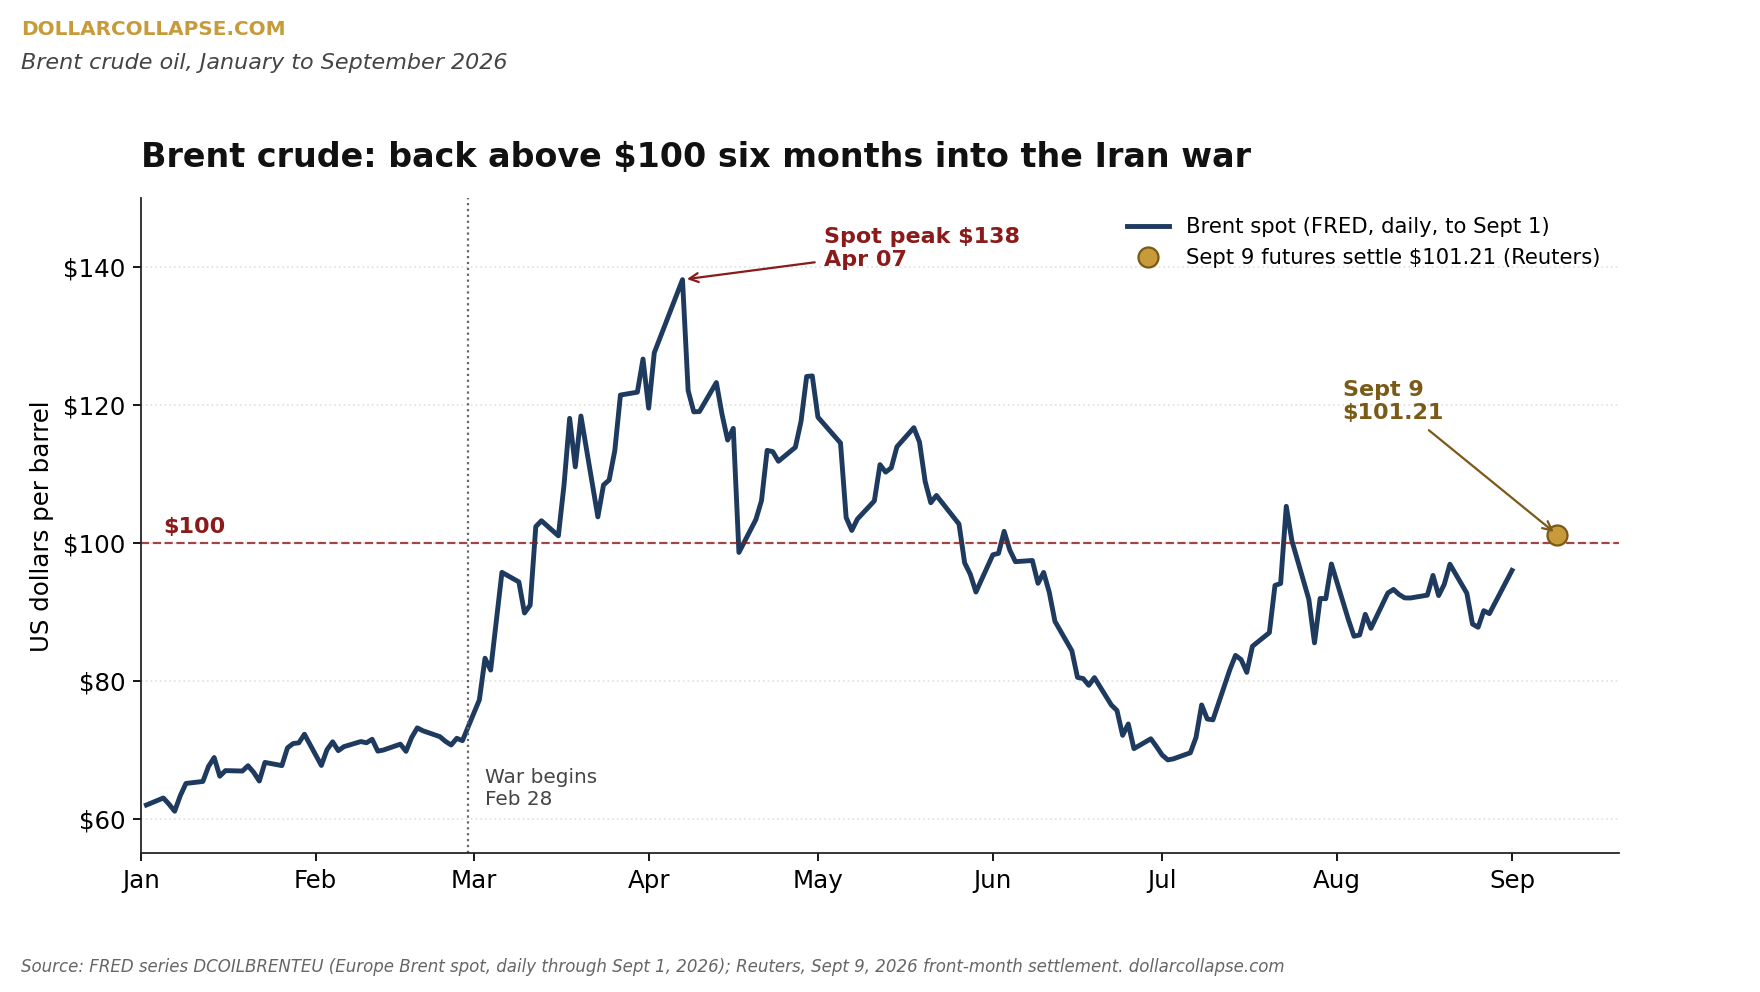
On September 9, Brent crude settled at $101.21, its highest close since May 22, after Iran and the United States struck tankers in the biggest wave of attacks on shipping since the war began in late February.
Reuters reported:
Brent settles at over $100 a barrel as Middle East conflict intensifies
Brent crude futures breached $100 a barrel on Wednesday to settle at their highest close since late May after Iran and the U.S. struck tankers in the biggest wave of attacks on shipping since the war began, threatening to worsen the disruption of energy supplies from the Middle East.
War in the Strait of Hormuz raises the threat to ships, and therefore raises crude oil prices on supply concerns. That’s because the route carries about one-fifth of the world’s oil and gas trade.
As a result, rising oil prices move inflation up, and then ripple through the rest of the economy with second and third order effects.
Oil Spreads Through the Economy
Higher oil prices reach far beyond the gas station. Diesel powers trucks, farm equipment, ships and construction machinery. Jet fuel sets the cost of air travel and freight. Petrochemicals go into plastics, packaging, fertilizer and thousands of consumer products.
When energy costs rise, a business has two choices:
- Accept lower profits.
- Or pass the cost to customers.
Most do some of both.
Recently passing that cost onto consumers hit the statistician reports.
American households have already paid about $100 billion in extra gasoline and diesel costs since the war began on February 28, according to a tracker run by Brown University’s Watson School. That works out to more than $760 per household, which is money spent at the pump ove restaurants, clothing or possibly the family vacation.
In a normal year the Fed would answer weak consumer spending by cutting interest rates, but $100 crude oil makes a cut like that dangerous.
The Fed’s Two Bad Choices
With the price of crude oil so high, here are the Fed’s limited options this week.
If the Fed cuts rates, it risks a weaker dollar and more fuel for inflation. Oil and most other commodities are priced in dollars, so a weaker dollar makes every imported barrel cost more.
If the Fed holds rates high, it squeezes households, businesses and the federal government. Mortgages, car loans and corporate borrowing stay expensive. Old debt gets harder to refinance.
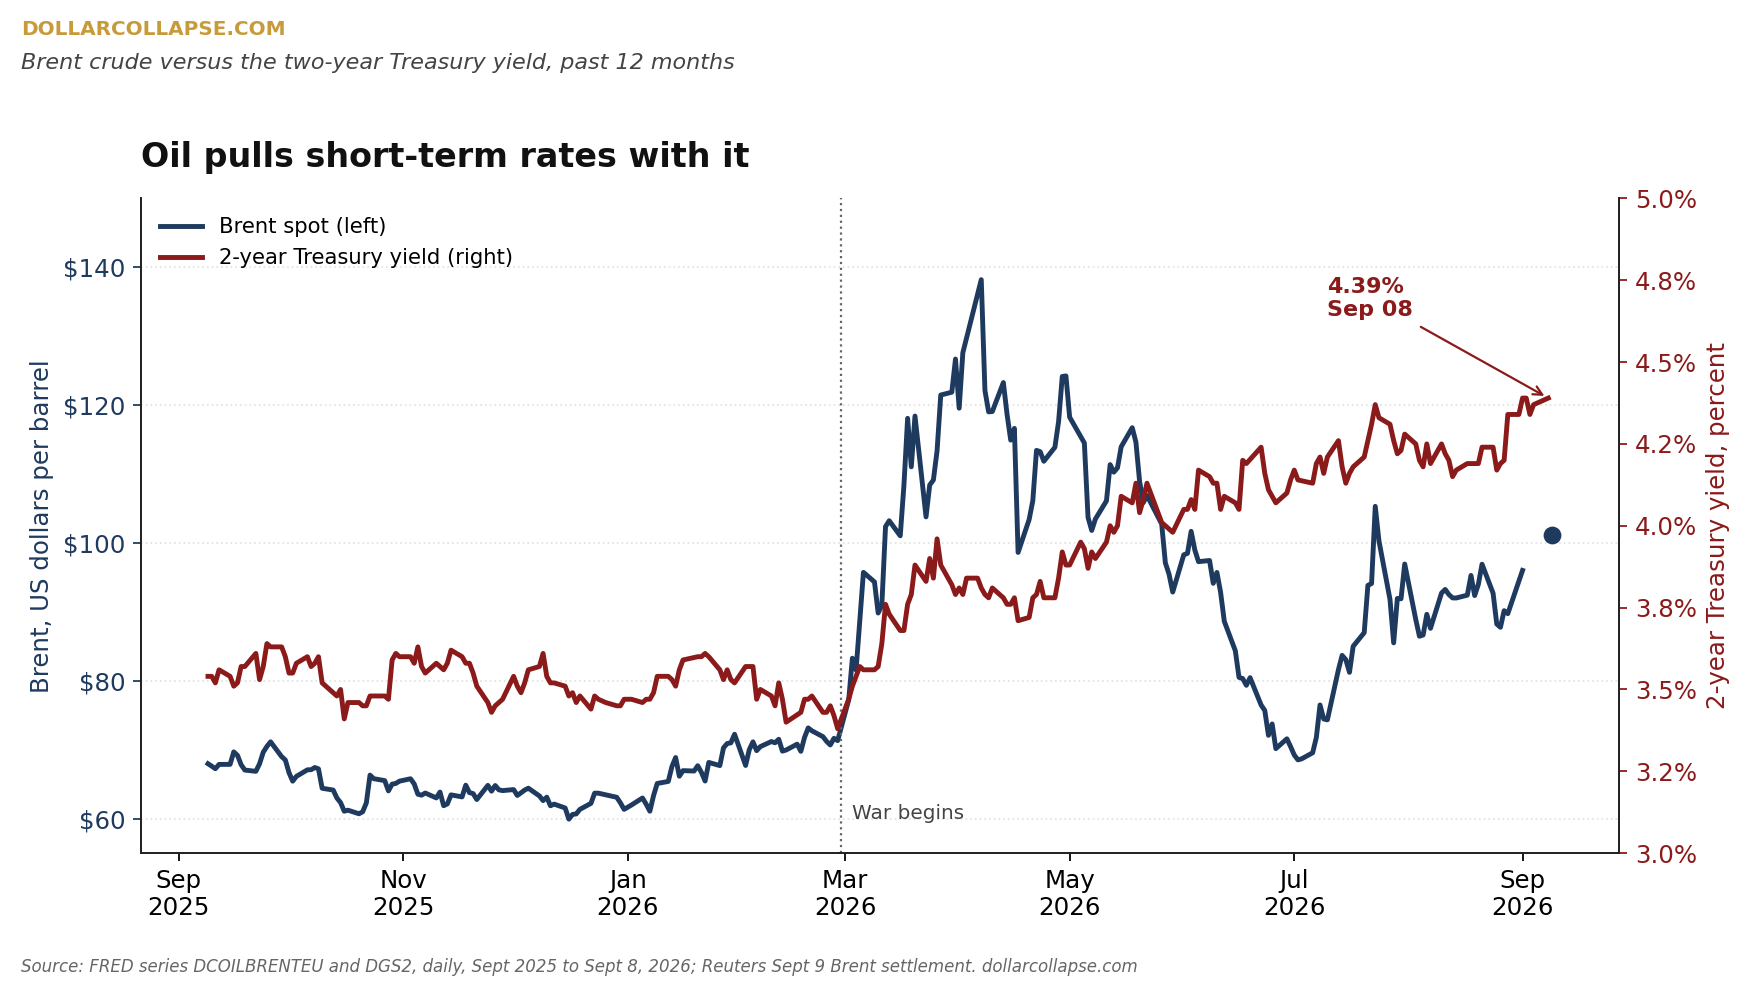
Whether or not the Fed makes decision to change interest rates this week, the bond market has already responding. As oil climbed back toward $100, the two-year Treasury yield rose to 4.39 percent and the ten-year yield ticked back above 4.8 percent on September 8. That being said, futures traders have spent the summer debating whether the Fed’s next move is a hike, not a cut; in mid-August CME FedWatch put the odds of a September hike near 30 percent.
The Fed is trapped no matter what they choose:
- Support the economy, and inflation gets room to run.
- Or fight inflation, and something built on cheap credit breaks.
The Fed has the power to choose where the pressure on the economy shows up, but because of US debt levels they can’t make the cost disappear. Something, or someone is either going to get hurt, or break.
Debt Makes Everything Harder
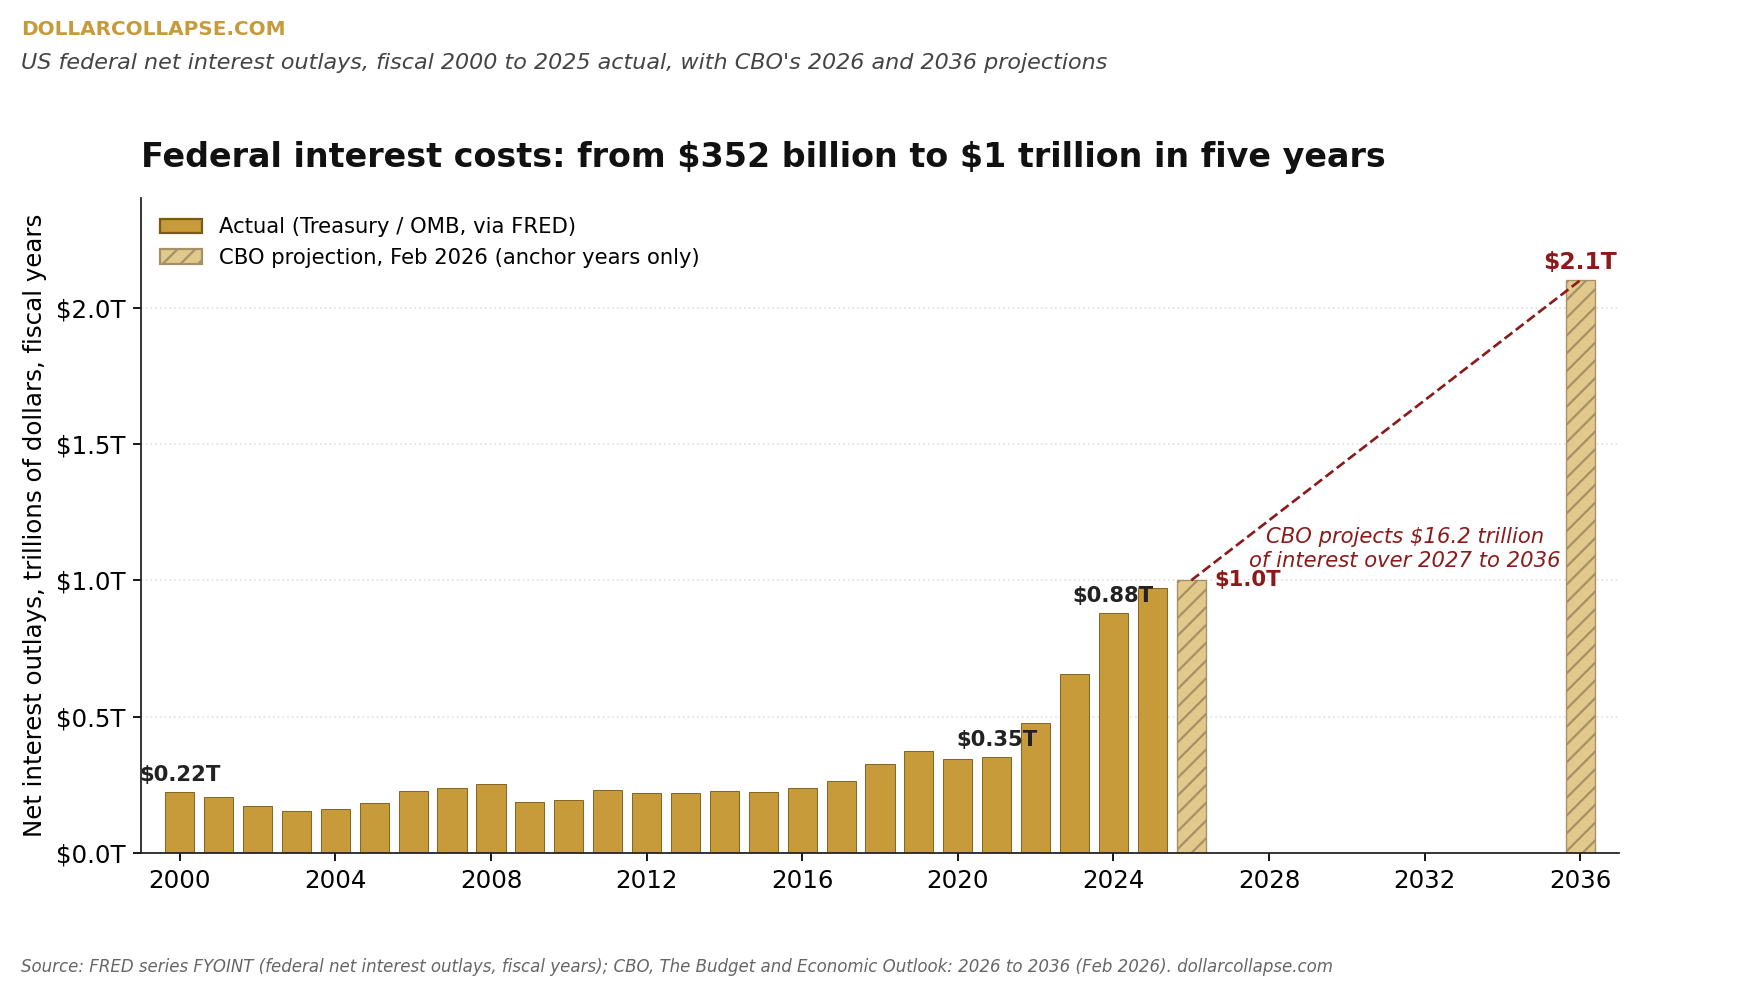
US debt is rising fast because the cost to service that debt is too high. On August 19, the United States entered an energy shock crisis with gross federal debt above $40 trillion. $40 Trillion came quickly. It was just a few years ago we were screaming $36 Trillion. The Congressional Budget Office expects net interest to cost $1.0 trillion this fiscal year and $2.1 trillion by 2036, or 4.6 percent of GDP.
How fast has the cost to service that debt go up, you ask?
Interest cost $352 billion as recently as 2021. Now were looking at $1 Trillion a year.
Higher Treasury yields make the cost to service that debt grow even faster. As old government debt matures, the Treasury replaces it with new debt at today’s higher rates.
That limits the Fed’s room to fight inflation. Back in the 1980s, the Fed could raise rates by several points without adding hundreds of billions of dollars to federal interest costs. Today, higher rates feed straight into bigger deficits, more Treasury issuance and still higher financing needs.
The Return of the No-Win Economy
Oil shocks alone do not cause monetary crises. But this one arrives when stock valuations are extreme, government debt is at a record highs, interest costs have doubled in four years and parts of the economy already strain under expensive credit. In only monetary terms, it is a three-part crisis.
The Fed has to protect the dollar, contain inflation, support employment, keep financial markets calm and help the Treasury finance a $40 trillion debt. It cannot do all of those at once.
This is how a debt-based monetary system gets trapped. Every fix creates a new problem.
Oil did not build the Fed’s impossible choice, but is making the elephant in the room harder to ignore.
